Sales of residential and commercial properties in Berlin rise to an annual high in the third quarter
Despite pressure from interest rates and political debates, the Berlin market recorded 187 individual sales. A look behind the scenes reveals what is driving the market.
High financing costs, regulatory debates and the political situation following the House of Representatives election are shaping the mood on the Berlin market for residential and commercial properties. Actual transactions paint a significantly more positive picture: according to figures from the Valuation Committee, 187 properties were sold individually in the third quarter of 2026 – more than in any other quarter of the year and more than in the same quarter of the previous year (186).
In the core market segment up to 20 million euros, turnover grew by a good eight per cent for the second quarter running. After nine months, this segment is therefore almost at the previous year’s level (down just under four per cent). Total turnover, including package sales, stood at around 2.03 billion euros – 29 per cent below the previous year – primarily because large-scale transactions and package sales generated significantly lower volumes.
Large-scale transactions dominate the year-on-year comparison
The decline in the overall market is concentrated in the high-volume segment. Revenue from package sales alone fell from around 573 to around 120 million euros in the first nine months. Added to this is a one-off effect from the previous year: in the third quarter of 2025, turnover in Tempelhof – largely driven by a major transaction – amounted to around 445 million euros. Consequently, the volume of individual sales in the third quarter of 2026, at around 688 million euros, was below the previous year’s figure of 1.10 billion euros.
Core market up to 20 million euros grows
For individual properties up to and including 20 million euros, turnover rose by just over eight per cent in the third quarter to around 542 million euros. This accounts for just under four-fifths of turnover from individual sales. After nine months, the segment totals around 1.32 billion euros, which is almost on a par with the previous year’s figure of 1.37 billion euros. The price bracket between 2.5 and 5 million euros was in particularly high demand: with 46 sales (Q3 2025: 39), the number of transactions rose by 18 per cent, whilst turnover increased by 16 per cent to around 166 million euros. Over the nine-month period, this price bracket, at around 405 million euros, is just under five per cent higher than the previous year and is the segment with the highest turnover.
Sales figures are also clearly on the rise: 127 individual sales in the first quarter were followed by 168 in the second and 187 in the third. Combined, the two most recent quarters, with 355 sales, have already exceeded the previous year’s figure of 350. The figures for the third quarter are still provisional and may rise further as a result of late registrations.
Favourable conditions for sellers and buyers
According to Engel & Völkers Commercial Berlin, this stability has structural causes. The market is largely characterised by private owners and families, whose decisions to sell tend to be driven by life stages rather than interest rates or politics. According to the company’s own surveys, motives such as retirement planning, succession or inheritance have accounted for around half of all sales for years.
Attractive entry opportunities are available for buyers. The firm’s own data from just under 100 sales this year shows that, following the 2023 and 2024 valuation adjustments, purchase prices will remain around 15 per cent below the 2025 average. Investors with solid equity positions are particularly well placed.
“Actual transactions are significantly better than the prevailing market sentiment,” says Benjamin Rogmans, Managing Director and Head of the Residential and Commercial Property Division at Engel & Völkers Commercial Berlin. “An owner who has held onto their property for 20 or 30 years won’t sell simply because interest rates or the political situation are changing. And those with equity to bring to the table now have access to properties and room for negotiation that haven’t been available for a long time. For owners and buyers alike, this is a good time to take action.”
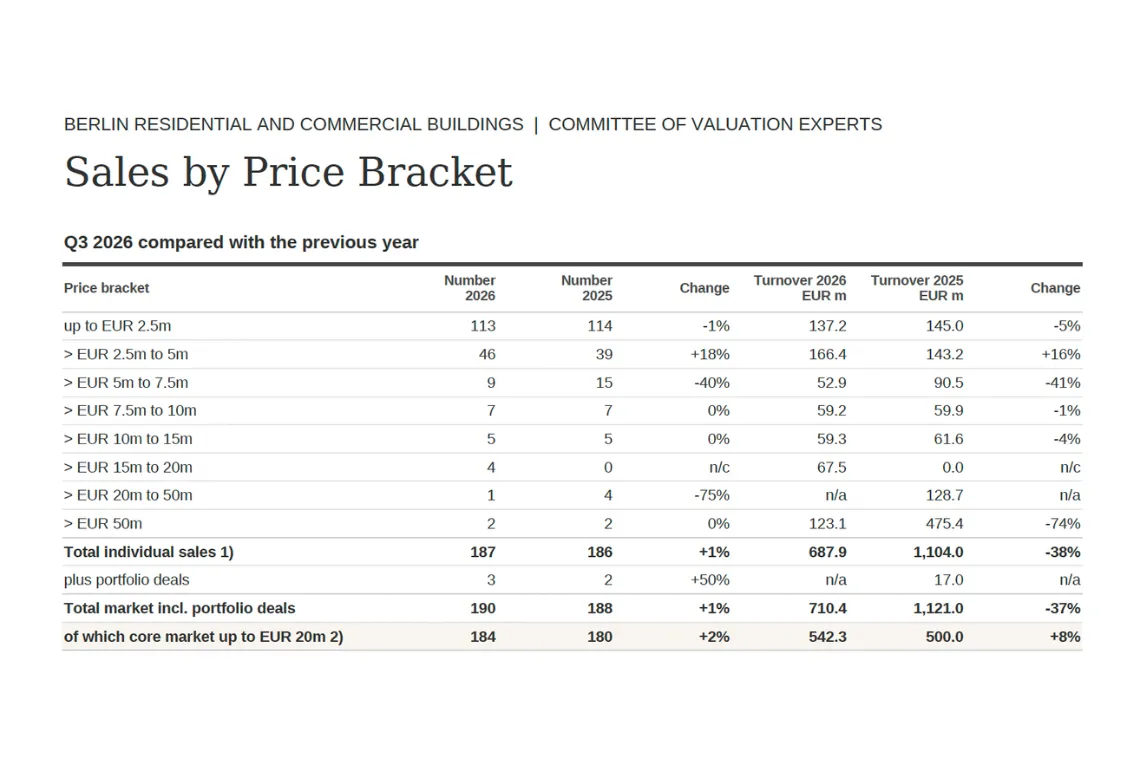
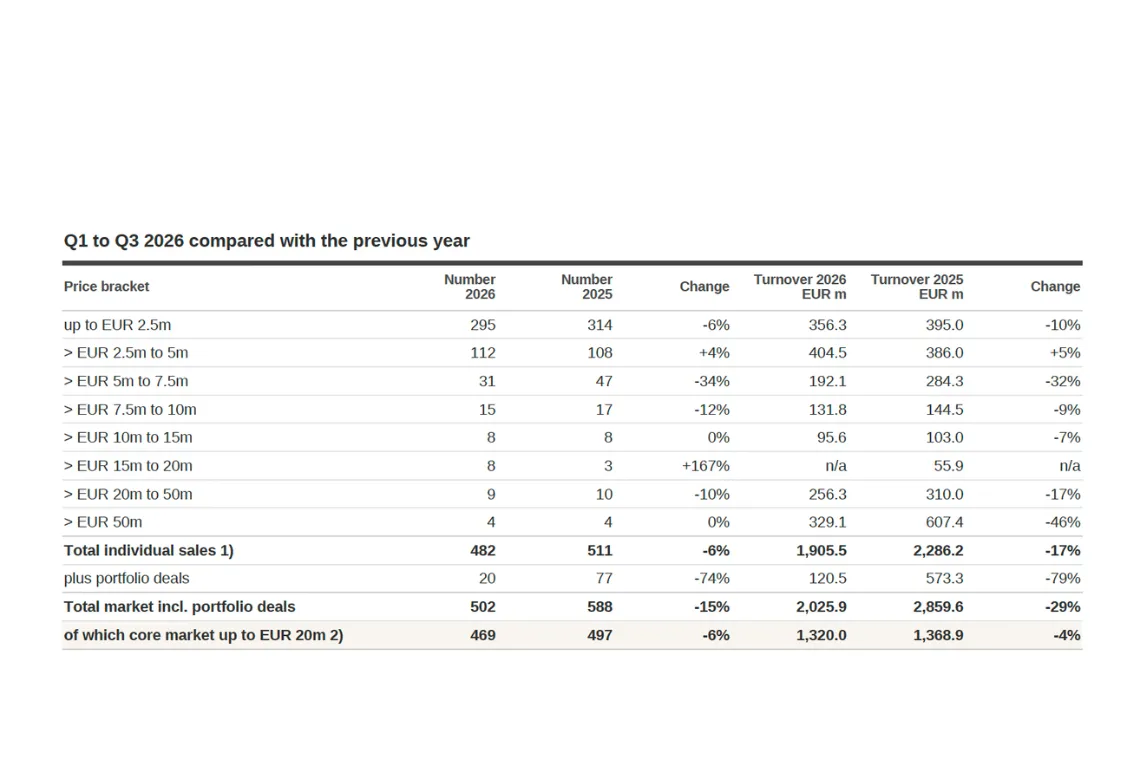
Source: Berlin Property Valuation Committee, Purchase Price Database; Presentation: Engel & Völkers Commercial Berlin.
Data retrieval date for 2026: 29 October 2026 (Q3 2026 provisional, late submissions possible), data retrieval date for 2025: 16 January 2026.
n/a = not available; individual purchase prices are not disclosed for data protection reasons. c/a = cannot be calculated, as the previous year’s figure was 0.
1) Total as reported by the Expert Committee; also includes individual values that have been withheld.
2) Total of individual sales, excluding those in the over €20 million category.
You may also be interested in