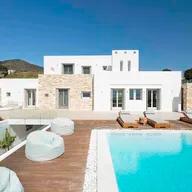
Vale do Lobo, Almancil, Faro District, Portugal
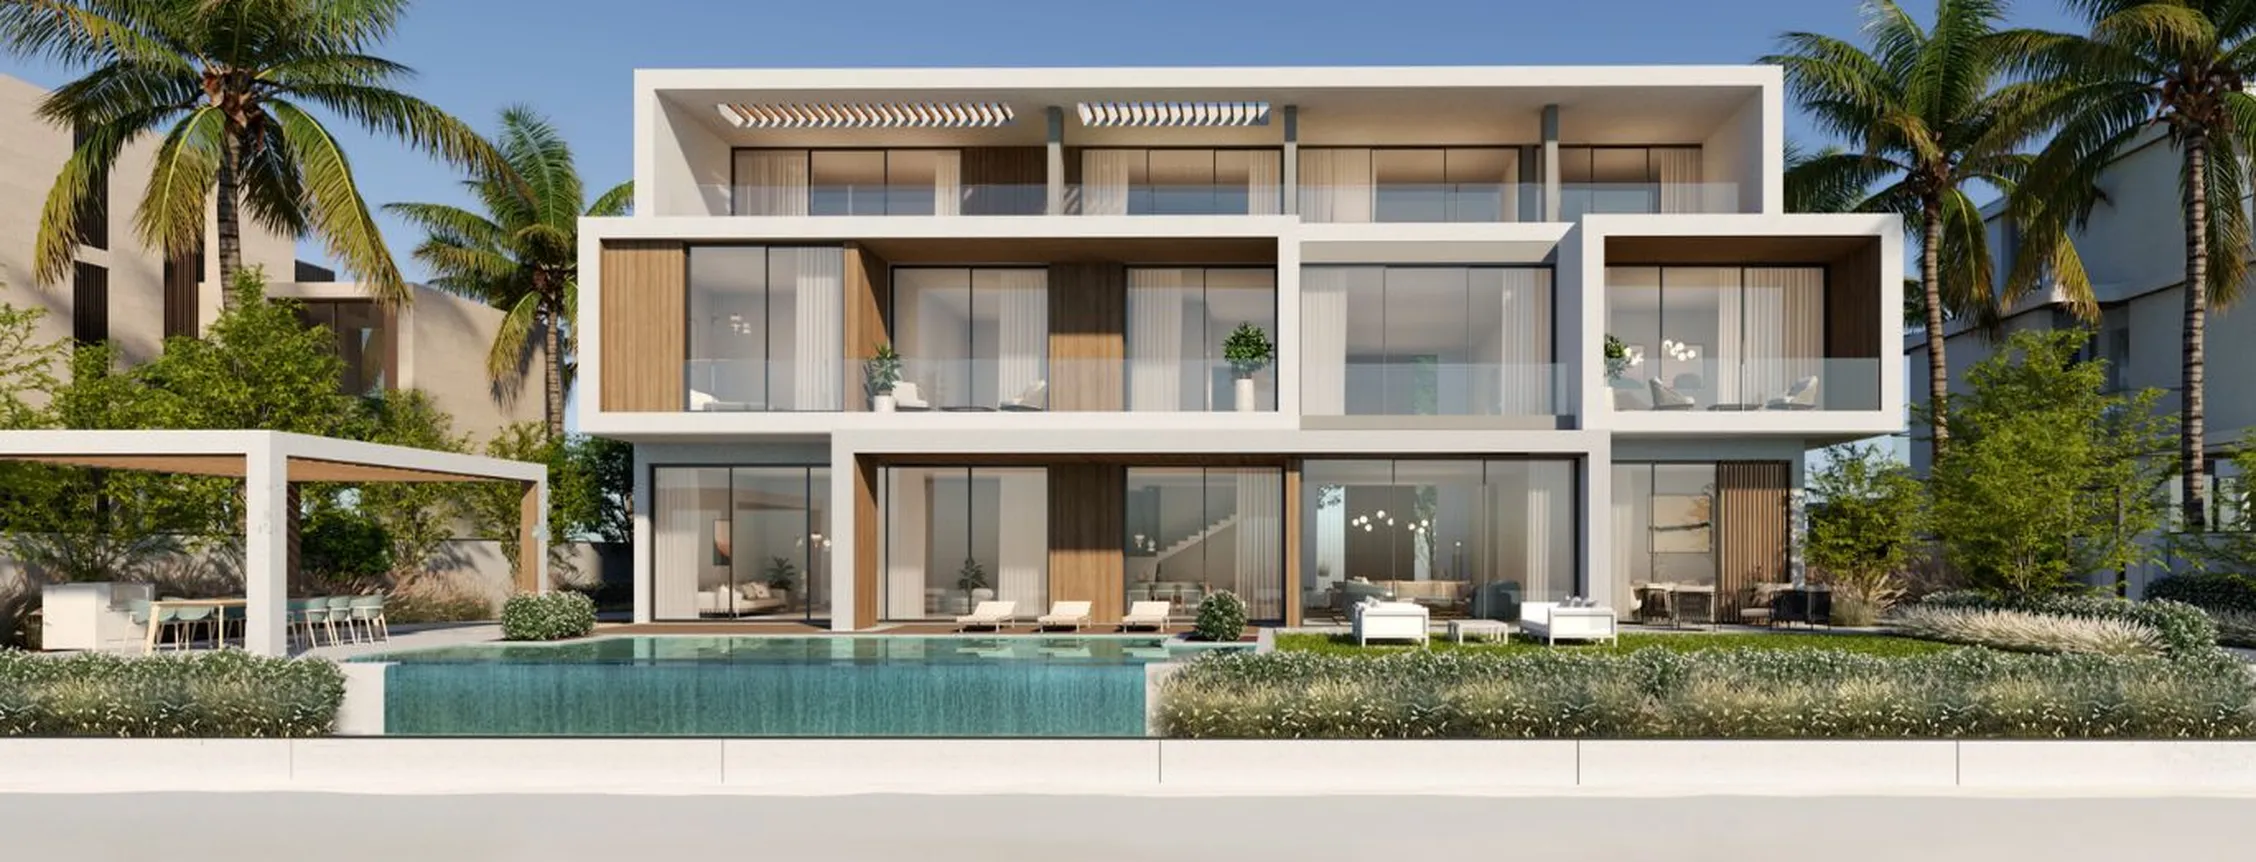
Magnificent Property with Sea Views and close to the Beach in Vale do Lobo
Price on request
- 12 Bedrooms
- 11 Bathrooms
- ~780 m² Living area
- ~7,220 m² Plot surface
Thinking about buying a second home? Explore the key factors to consider, from property prices and financing to location, investment potential and costs.
Buying a second home in Portugal is a decision that combines personal, financial and property investment objectives. For some families, it means having a holiday home where they can spend weekends and enjoy time away. For others, it represents an opportunity to invest in a property with potential for capital appreciation or to generate income through rentals. However, in a property market characterised by rising prices and different financing conditions, an important question arises: is now the right time to buy?
The answer depends on factors such as financial capacity, preferred location, intended use and expectations for the property. Rather than attempting to predict future price movements, it is important to understand whether the purchase makes sense in each buyer's circumstances. To start exploring the possibilities, prospective buyers can browse the houses for sale in Portugal available through Engel & Völkers and discover different types of properties suitable for a second home.
Table of Content
Does buying a second home in Portugal still make sense?
What is happening in the Portuguese property market?
Define the purpose of your second home before starting your search
How can you determine whether you can afford a second home?
Mortgages for second homes: what are the differences?
What taxes apply when buying a second home?
The costs of owning a second home go beyond the purchase
Buying a holiday home or continuing to rent?
Where should you buy a second home in Portugal?
How to assess a location before buying
Buying a new or existing second home?
Should potential property appreciation influence the decision?
Can a second home generate rental income?
How to calculate the real return on a second home
What should you check when viewing a second home?
Which documents should be checked before buying?
Buy now or wait for property prices to fall?
When might it be better to postpone the purchase?
Five questions to determine whether now is the right time
The importance of choosing the right property
Is buying a second home worthwhile right now?
Frequently asked questions
A second home can serve different purposes throughout life. It may initially be a holiday property used for a few weeks each year and later become a residence for extended stays or even retirement.
This flexibility is one of the reasons why purchasing a second property continues to attract interest.
Portugal offers several characteristics that make this type of purchase particularly appealing: diverse landscapes, a relatively mild climate, coastal regions, historic cities and rural areas with distinctive property options.
However, the advantages of owning a second property should be assessed alongside the financial and practical responsibilities involved.
Unlike a holiday or an occasional stay in tourist accommodation, buying a house represents a long-term commitment, with expenses that continue even when the property is not being used.
The decision should therefore begin with a simple question: what will be the real purpose of this second home?
Recent developments in house prices are among the main factors to consider before buying a second property.
According to data from Statistics Portugal (INE), published in September 2026, the House Price Index increased by 16.5% in the second quarter of 2026 compared with the same period of the previous year.
The increase was more pronounced for existing homes, with year-on-year growth of 18%, while prices for newly built properties rose by 12.3%.
During the same quarter, 40,142 homes were sold, representing a 6.4% decrease compared with the corresponding period of the previous year.
These figures reveal a market in which prices continued to rise despite a reduction in transaction volumes.
However, these indicators should not be interpreted as an automatic prediction of future price movements. National trends do not mean that every region, property type or market segment is experiencing exactly the same conditions.
The urban apartment market may behave differently from the market for coastal villas or rural holiday properties.
Anyone considering buying a second home should therefore carefully analyse local market conditions.
The right time to buy may depend more on finding a property with attractive characteristics at a price consistent with the market than on attempting to identify the lowest point of a property cycle.
One of the most important decisions should be made before viewing properties.
The intended purpose of a second home influences almost every aspect of the purchase, including location, property type, budget, financing and potential appreciation.
When the main objective is leisure, priority should be given to the quality of the experience the property offers.
Distance from the primary residence, accessibility and the availability of nearby services may be more important than the size of the house.
A second home located two hours away can be used regularly throughout the year. By contrast, a property requiring long or expensive journeys may end up being reserved exclusively for longer holidays.
Maintenance should also be considered. An apartment in a condominium with shared services may be more practical for occasional stays than a detached house with a large garden and private swimming pool.
Some families purchase a second home with the intention of using it more frequently after retirement.
In this situation, features that initially seem secondary may become essential later in life.
Proximity to healthcare services, accessibility within the property, year-round shops and transport options should all be considered.
A home that works perfectly for a two-week summer holiday may not be equally comfortable for several months of winter living.
When there is an intention to rent out the property, the analysis should include demand, seasonality and operating costs.
Potential rental income can help cover certain expenses, but it should not be confused with guaranteed returns.
The location and type of property should be appropriate for the intended rental strategy.
Buying a second property requires a different financial assessment from the one normally associated with purchasing a primary residence.
The buyer may already have mortgage repayments, regular household expenses and other financial commitments.
Adding a second property increases real estate assets but also creates additional costs.
Before proceeding, it is important to answer several questions:
Is there enough capital available for the deposit and property purchase taxes?
Will the purchase compromise savings reserved for emergencies?
Can the ongoing costs be covered without relying on rental income?
What would be the impact of a potential increase in mortgage repayments?
Could the property be maintained for several years without needing to sell urgently?
A second home should be regarded as a decision that is compatible with financial stability, rather than a commitment that requires sacrificing other essential needs.
It is equally important to preserve some liquidity after the purchase. Property represents an asset, but it cannot necessarily be sold immediately at the desired price.
One of the most important questions for buyers who intend to use financing is how much the bank may be willing to lend.
According to Banco de Portugal's macroprudential recommendations, financing for the purchase of a primary and permanent residence should generally not exceed 90% of the lower of the purchase price and the bank's property valuation.
When the loan has another purpose, including the purchase of a second home, the recommended limit is 80%.
This means that someone intending to buy a second home should generally have enough capital to cover at least 20% of the value considered by the bank, in addition to the purchase expenses.
Consider a second home with a purchase price of €300,000.
If the bank's valuation matches the purchase price and financing reaches 80%, the mortgage could amount to €240,000.
The buyer would need to provide the remaining €60,000 from personal funds, plus taxes and other expenses.
If the bank's valuation is lower than the agreed purchase price, financing will be calculated using that lower amount, which may increase the required down payment.
This example is for illustration purposes only. Approval also depends on financial capacity, credit history and the conditions established by the financial institution.
The choice of interest rate also influences how predictable mortgage repayments will be.
A fixed interest rate provides greater stability during the agreed period. A variable rate follows changes in the reference index specified in the contract, usually linked to Euribor.
A mixed rate combines an initial fixed-rate period with a subsequent variable-rate phase.
None of these options is universally better. The decision should consider risk tolerance, loan duration and the specific conditions offered by the bank.
It is advisable to compare the annual percentage rate of charge (APR), known in Portugal as TAEG, and the total amount payable by the consumer, rather than focusing exclusively on the advertised monthly repayment.
Taxation is one of the aspects that most clearly distinguishes the purchase of a second home from the acquisition of a primary residence.
In Portugal, buying a second property is generally subject to Property Transfer Tax, known as IMT, and Stamp Duty.
IMT is calculated according to the rules applicable to the type of property, its location and the taxable value of the transaction.
For a second home intended for residential use, the rates applicable to properties used exclusively for housing that are not classified as primary and permanent residences generally apply.
The taxable amount is usually based on the higher of two values: the declared purchase price or the property's taxable value, known as Valor Patrimonial Tributário (VPT).
The applicable rates and thresholds should be checked at the time of purchase, as they may be updated.
Property purchases are also subject to Stamp Duty, generally charged at 0.8% of the amount used as the tax base.
When bank financing is involved, additional taxes associated with the mortgage may apply, depending on the characteristics and duration of the agreement.
The IMT and Stamp Duty exemption associated with the IMT Jovem scheme is intended, subject to the legal requirements, for the first purchase of a primary and permanent residence by eligible buyers aged 35 or under.
Therefore, purchasing a genuine second home for holidays or occasional use does not generally qualify for this scheme.
This distinction should be considered when setting the budget, as property purchase taxes can represent a significant expense at completion.
The purchase price represents only part of the investment required.
A second home involves ongoing expenses that must be considered regardless of how frequently the property is used.
Municipal Property Tax, known as IMI, is one of these responsibilities.
In Portugal, the general IMI rate for urban properties ranges from 0.3% to 0.45% of the property's taxable value, although specific circumstances and legally established increases may apply. The actual rate is determined by the municipality within the applicable limits.
In addition to IMI, homeowners should consider condominium fees, insurance, water, electricity, telecommunications and maintenance.
For houses with swimming pools or gardens, these costs can be particularly significant.
A property used only on occasional weekends still requires cleaning, ventilation, equipment inspections and attention to potential problems.
The annual budget should also include a reserve for unexpected repairs, appliance replacements or building maintenance.
The objective is to understand the property's actual cost of ownership and use, rather than focusing exclusively on mortgage repayments.
Buying is not always the most suitable solution.
For someone who visits a particular region for only one or two weeks each year, continuing to use holiday accommodation may provide greater financial flexibility.
Short-term accommodation allows travellers to explore different destinations and avoids the permanent maintenance costs associated with property ownership.
On the other hand, a second home offers stability, freedom of use and the opportunity to personalise the space.
It also eliminates the need to search for accommodation for every trip and can make more frequent stays easier.
The decision should consider how often the property will actually be used.
A practical way to evaluate this is to estimate how many nights per year the household expects to spend in the property and compare the annual ownership costs with the accommodation expenses that would otherwise be incurred.
This comparison should not ignore the opportunity cost of the capital invested or the possibility of property appreciation or depreciation.
Buying can provide benefits that are not exclusively financial, but those advantages should be assessed consciously.
Choosing the location is one of the decisions with the greatest impact on the experience of using the property and its potential future value.
Portugal has property markets with very different characteristics, meaning there is no single ideal region for every buyer.
The Algarve remains a popular region for holidays and second homes, with properties ranging from apartments close to the sea to residential villas and premium homes.
Proximity to beaches, tourist services and good accessibility are among the factors to consider.
However, it is important to understand the differences between individual locations. Some areas remain active throughout the year, while others experience strongly seasonal demand.
Areas close to Lisbon can appeal to buyers who want to combine a second home with access to services, culture and urban activities.
Cascais, for example, has different characteristics from locations south of the Tagus River or areas further away from the capital.
The decision should consider travel times, available properties and the intended type of use.
In northern Portugal, options include coastal properties, homes in small towns and houses in mountain areas or surrounded by natural landscapes.
The Douro Valley, Minho and different parts of the northern coastline can appeal to different buyer profiles.
The smaller size of certain towns can offer tranquillity, but makes it even more important to assess local services, accessibility and maintenance requirements.
The Alentejo can attract buyers who value privacy, large plots of land and a slower pace of life.
Country estates, traditional houses and rural properties are among the options available in the region.
When buying this type of property, it is essential to assess access roads, water supply, land maintenance and urban planning regulations.
Portugal's autonomous regions offer possibilities for buyers seeking a second home in an island setting.
The landscapes, climate and opportunities for extended stays can contribute to the appeal of these destinations.
However, travel costs, flight availability and the distance from the primary residence should be part of the decision.
The most suitable property will not necessarily be the one located in a favourite holiday destination. It will be the one whose location, price and characteristics best match the buyer's lifestyle and objectives.
Visiting a region during a holiday provides only a partial perspective of its conditions.
A town that is busy during summer may become significantly quieter in winter. This may be positive for some buyers but less attractive to others.
Before deciding, it is advisable to visit the area at different times of the year and assess how everyday life functions.
The availability of supermarkets, pharmacies, healthcare services, restaurants and public transport should be checked.
The quality of access roads should also be assessed during periods of heavier traffic.
In coastal areas, proximity to the sea can be an important advantage, but should be considered alongside exposure to humidity, corrosion and other environmental factors.
In rural regions, vegetation management, wildfire risk and access road maintenance may be particularly relevant.
A good location should be evaluated both for the experience it offers during holidays and for how easy the property will be to use and maintain throughout the year.
The Portuguese market offers opportunities in both new-build and existing properties, but each option has characteristics that should be considered.
A newly built home may provide energy-efficient solutions, modern finishes and a reduced need for immediate maintenance.
On the other hand, it may have a higher purchase price or involve a waiting period if construction has not yet been completed.
An existing second home can offer greater variety in terms of locations, sizes and architectural styles.
In certain areas, older properties are located in established neighbourhoods, close to historic centres or beaches where new construction opportunities are limited.
However, it is necessary to carefully assess the property's condition, energy efficiency and potential renovation costs.
When purchasing an off-plan property, it is important to understand the contractual conditions, expected completion dates and risks associated with possible delays.
For anyone considering investing in a brand-new property, understanding the main criteria for choosing apartments under construction in Portugal can help support a more informed decision.
A second home can represent an important component of a family's assets, but future appreciation should never be taken for granted.
Changes in property values depend on factors such as location, supply, demand, economic conditions, property quality and regional development.
A house in an area with established transport connections and year-round services may have different demand characteristics from a property in a highly seasonal destination.
It is also important to distinguish between nominal appreciation and actual investment returns.
If a property's value increases over the years, that growth should be assessed after considering purchase taxes, annual expenses, maintenance costs, renovations and any costs associated with a future sale.
An apparently attractive increase in value may become less significant once all these elements are taken into account.
Therefore, the primary purchasing criterion should remain how well the property matches the buyer's objectives and financial capacity.
One of the advantages frequently associated with buying a second home is the possibility of generating income during periods when the owner is not using it.
This option can help cover some of the property's expenses, particularly in locations with tourist or residential rental demand.
However, profitability depends on several factors and requires a realistic assessment.
The homeowner should consider expected occupancy, rental rates, platform or intermediary commissions, cleaning costs, maintenance and applicable taxes.
It is also important to decide whether the property will be offered for long-term residential rental, shorter fixed-term arrangements or tourist accommodation.
In Portugal, short-term tourist accommodation, known as Alojamento Local (AL), is subject to a specific legal framework.
Decree-Law No. 76/2024 introduced significant changes to the system, including amendments to registration requirements and municipal powers.
Local authorities may establish specific regulations and restrictions, so the feasibility of operating tourist accommodation should be confirmed for the property's exact location.
In an update published in September 2026, the gov.pt portal clarified that local accommodation registration is completed through a prior notification procedure with a deadline, and that different periods may apply for municipal objections.
Before purchasing a second home with the intention of operating it as tourist accommodation, it is essential to confirm that the proposed use is legally permitted.
Buying based on projected rental income without verifying these conditions may compromise the viability of the investment.
The profitability of a rental property should be assessed using both income and expenses, rather than simply the potential value of bookings.
Imagine a second home generating €12,000 per year in gross rental income.
This amount does not represent the homeowner's profit.
Maintenance expenses, cleaning, condominium charges, insurance, taxes, management fees and other applicable costs must be considered.
Calculating the net return requires using the amount actually available after expenses and comparing it with the capital invested.
Periods without occupancy and potential extraordinary expenses should also be taken into account.
A prudent assessment should include different scenarios: a favourable scenario, a moderate one and another in which demand is lower than expected.
The second home should remain financially sustainable even when rental income falls short of projections.
A property viewing intended for a holiday home should go beyond appearance and surroundings.
A house may seem perfect during a summer visit but reveal less practical characteristics at other times of the year.
It is important to inspect the condition of walls, signs of damp, window quality, ventilation and thermal insulation.
Solar orientation can also have a significant impact on comfort.
A house with large glazed surfaces and little solar protection may require greater use of air conditioning during warmer months.
In apartments, the condition of communal areas and any planned condominium work should be assessed.
For detached houses, particular attention should be given to roofs, drainage systems, swimming pools and outdoor spaces.
Another relevant issue is security during extended periods of absence.
A property used only occasionally may benefit from security solutions, maintenance services and local support, but these options should be included in the budget.
Documentation is essential for confirming the property's legal status and characteristics.
Commonly relevant documents include the permanent land registry certificate, property tax registration certificate, energy performance certificate and available urban planning documentation.
Any existing mortgages, seizures, easements or other encumbrances should also be checked.
If the property is part of a condominium, it is advisable to assess regular charges, potential outstanding debts and planned extraordinary maintenance work.
Unlicensed construction work or discrepancies between registered areas and the property's physical characteristics may require further clarification.
Although legislative changes in 2024 simplified certain transfer procedures, this does not remove the importance of checking the property's urban planning status.
Buyers should understand exactly what they are purchasing and the legal conditions governing the property's use.
This is one of the most difficult questions to answer.
In a market where prices have recorded significant increases, delaying a purchase in anticipation of a correction may seem tempting.
However, there is no guarantee that prices will fall in a particular region or that any eventual reduction will coincide with the availability of the desired type of property.
Prices may also stabilise, continue rising or develop differently depending on location.
Waiting exclusively for a general market downturn may therefore not be the most appropriate strategy.
A more informed approach involves defining a budget, researching current prices and monitoring properties that meet specific criteria.
If a property becomes available with hard-to-find characteristics, a market-appropriate price and favourable financial conditions, proceeding with the purchase may make sense.
Conversely, when buying depends on excessively demanding financing or uncertain future income, postponing the decision may be more prudent.
The right time should result from a combination of property opportunity and financial readiness.
There are circumstances in which waiting may be the most appropriate decision, even when the desire to own a second home is strong.
Insufficient funds for the initial deposit, a lack of emergency savings or high levels of existing debt are signs that finances may need to be reorganised before proceeding.
It is also advisable to delay the decision when significant doubts remain about the location.
Buying in a region simply because it provided an enjoyable holiday may not be enough to justify a long-term investment.
A lack of clarity about the property's intended purpose represents another risk factor.
A home purchased for family use may not have the characteristics needed to generate the rental income initially expected.
Similarly, buying exclusively out of fear that prices will continue to rise may lead to rushed decisions.
A second home should provide freedom and quality of life rather than becoming a permanent source of financial pressure.
Before proceeding with a purchase, it may be useful to conduct a personal assessment based on five essential questions.
Will I use this property frequently? The expected level of use should justify the financial and practical commitment involved in owning the property.
Can I afford all the expenses without relying on rental income? The purchase will be more sustainable if potential rental income is treated as an additional benefit rather than a necessity.
Do I truly know the location? A well-informed decision should consider different seasons, accessibility and available services.
Is the price consistent with the market? A well-founded valuation can reduce the risk of paying more than the property is worth.
Do I intend to keep this property for several years? A longer ownership horizon can help justify the initial acquisition costs and reduce dependence on short-term market fluctuations.
These questions do not replace a complete financial and legal assessment, but they can help determine whether the purchase is aligned with the household's objectives.
The decision to purchase a second home should not be based exclusively on general market conditions.
Two houses with similar prices may represent very different opportunities because of their location, condition, maintenance costs and potential uses.
Specialist real estate support can help identify properties suited to the buyer's profile and provide a clearer understanding of the differences between available options.
For a second home, factors such as ease of remote maintenance, the quality of the surrounding area and the possibility of using the property throughout the year can be particularly important.
Engel & Völkers offers a diverse selection of residential properties for sale in Portugal, allowing buyers to explore different locations, property types and characteristics.
The decision should prioritise properties that make sense not only at the moment of purchase but also in the years that follow.
Buying a second home can still make sense for those who have financial stability, understand the market in which they intend to invest and have clear objectives for using the property.
Recent price growth reinforces the importance of avoiding rushed decisions and assessing each opportunity individually. Understanding market indicators can contribute to a more informed choice. The Engel & Völkers Market Study provides information on relevant trends and developments in the Portuguese property market, helping buyers put purchasing conditions in different locations into perspective.
Rather than searching for a universal answer about the best time to buy, the priority should be finding the right property, in the right location and within a sustainable budget. For anyone considering purchasing a second residence, exploring the properties available through Engel & Völkers and benefiting from specialist support can be a first step towards turning that objective into an informed decision suited to personal needs.
PROPERTIES IN PORTUGAL
Vale do Lobo, Almancil, Faro District, Portugal
Price on request
Quinta do Lago, Almancil, Faro District, Portugal
Price on request
Centro Historico, Cascais, Lisbon, Portugal
Price
€22,000,000
Porto, Porto District, Portugal
Price on request
Albufeira, Faro District, Portugal
Price
€18,500,000
Faro, Faro District, Portugal
Price
€18,000,000
Carnaxide, Lisbon, Portugal
Price
€17,000,000
Quinta do Lago, Almancil, Faro District, Portugal
Price
€15,750,000
Quinta do Lago, Almancil, Faro District, Portugal
Price on request
A primary and permanent residence generally refers to a property used as the household's habitual home, in accordance with applicable legal requirements. A second home is a property used for holidays, weekends, occasional stays or other purposes that do not correspond to the main residence. This distinction has important consequences, particularly regarding financing and taxation. Mortgage conditions may differ, and certain tax benefits are reserved for the purchase of a primary and permanent residence. It is also important to understand that the classification does not depend solely on the designation used by the homeowner, but on the property's actual purpose and compliance with legal requirements. Before purchasing, the intended use and corresponding legal classification should be confirmed.
Yes. An individual can have two mortgages for purchasing properties, provided they meet the requirements established by the financial institutions. Approval of a second mortgage depends on an assessment of income, existing financial commitments, credit history and repayment capacity. The bank will consider repayments on existing loans when evaluating the applicant's debt burden. In addition, financing for a second home is generally subject to a recommended limit of 80% of the lower of the purchase price and the bank's property valuation. Having an existing mortgage does not automatically prevent someone from obtaining another, but it may reduce the amount available and require a larger down payment.
There is no general IMI tax rate that applies exclusively because a property is a second home. The tax generally depends on the property's taxable value and the rate established by the municipality, although specific benefits, increases or other legal provisions may apply. The main difference may arise from eligibility for certain exemptions, which are often associated with primary and permanent residences and subject to specific requirements. A second home may not qualify for these schemes. The Additional Municipal Property Tax, known as AIMI, should also be considered when the owner's real estate assets fall within the legal conditions for taxation. Before purchasing, it is advisable to check the property's taxable value and estimate the annual tax liability.
Yes, provided the property genuinely meets the conditions required to become the habitual residence and the applicable administrative and tax obligations are fulfilled. This change may be relevant for someone who originally purchased a holiday home and later intends to use it as a permanent residence. However, changing the property's purpose does not mean that all tax benefits associated with the initial purchase of a primary and permanent residence can be applied retroactively. There may also be implications for mortgage financing and future taxation. Before making the change, it is advisable to confirm the requirements with the relevant authorities and assess the specific tax implications.
The choice depends on available liquidity, borrowing costs and the buyer's financial objectives. Purchasing outright eliminates mortgage interest and monthly repayments, but requires using a significant proportion of available capital. Mortgage financing allows buyers to preserve some of that liquidity, although it increases the total cost of acquisition. It is important to assess interest rates, contractual expenses and the ability to afford repayments over time. A financial reserve for unexpected expenses should also be maintained. The best solution is not necessarily the one that reduces borrowing to the absolute minimum, but the one that provides an appropriate balance between assets, liquidity, risk and financial stability.
Yes, provided the intended rental arrangement complies with the applicable legal rules. The legal framework may differ depending on whether the property is used for residential rental or to provide temporary tourist accommodation services. In the case of Alojamento Local, specific registration, notification and operating requirements apply, along with potential municipal restrictions. The homeowner should confirm the rules in force before advertising the property on booking platforms. Taxation of rental income, reporting obligations and management expenses must also be considered. The fact that a property is only used occasionally by its owner does not automatically mean it can be operated as tourist accommodation without meeting the necessary requirements.
A second home close to the sea can offer advantages for personal use and attract interest from certain buyers, but proximity to the beach does not guarantee capital appreciation or profitability. Access, available services, property condition, year-round demand and maintenance costs are equally important factors. In coastal areas, exposure to humidity, corrosion and certain environmental risks may increase maintenance requirements. It is also necessary to assess the asking price in comparison with similar properties. For a purchase intended primarily for holidays, the quality of life provided may justify part of the investment, but that personal benefit should be distinguished from the expected financial return.
Yes. Joint ownership can allow family members or other individuals to share the initial investment and regular expenses. However, it is important to define each owner's responsibilities in advance. Matters such as sharing costs, allocating periods of use, making decisions about renovation work and establishing the conditions of a future sale should be discussed before completion. It is also advisable to consider what happens if one co-owner wishes to sell their share or stops contributing to expenses. Although joint purchasing can make it easier to acquire a more attractive property, it requires communication and clear rules. Legal support can help structure the arrangement and prevent future disputes.
You may also be interested in
FOR MORE INFORMATION
Engel & Völkers Portugal
Av. da Liberdade 196, 7 andar
1250-096 Lisboa, Portugal
Tel: +351 210 200 490