New
- 5 min read
Selling a home to a real estate investment fund: advantages and points to consider
Understand the advantages, the risks and the key points to analyse before accepting a proposal from a real estate investment fund
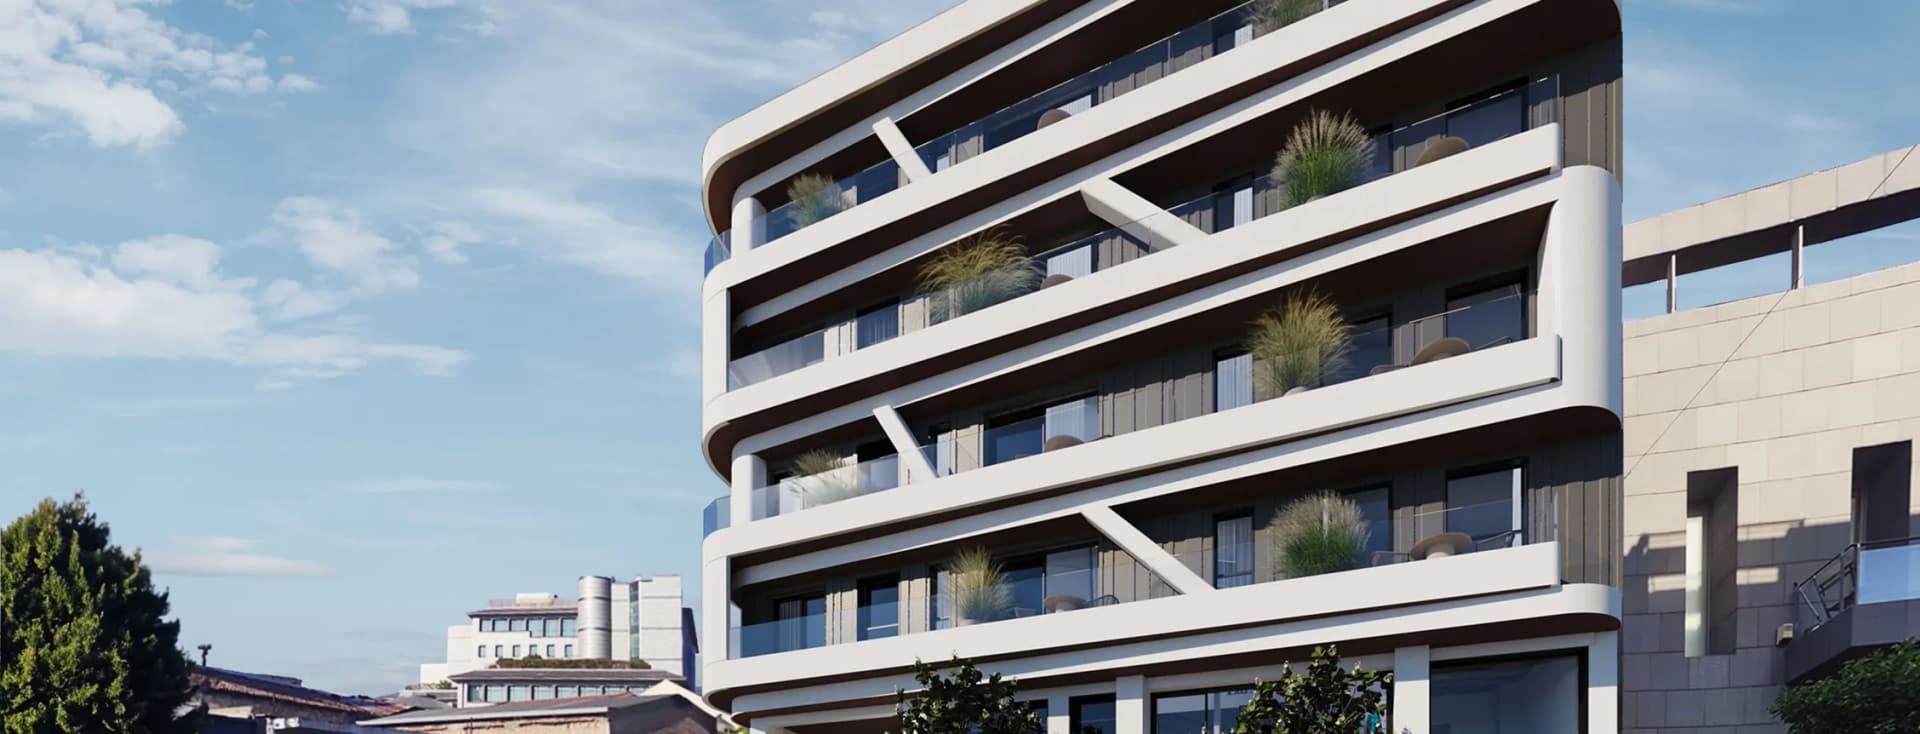
In recent years, real estate investment funds have become increasingly active buyers in the Portuguese residential market. What was once a phenomenon confined to commercial property, offices, shopping centres and logistics assets, has progressively expanded into the housing market, with funds acquiring portfolios of apartments, houses and even entire developments in cities such as Lisbon and Porto and in the country's main tourist areas.
For a seller considering their options, the possibility of having an investment fund on the other side of the transaction raises legitimate questions. Is it a good option? What advantages does it offer compared to selling to a private buyer? Which points should be analysed carefully before accepting this type of proposal?
This article answers these questions in detail, addressing the Portuguese market context, the specificities of a transaction with an investment fund and the factors a seller must consider before making a decision.
Table of Content
What are real estate investment funds and how do they operate in Portugal
The advantages of selling to an investment fund
Points to consider carefully
How to position the sale: open market versus direct transaction
The regulatory context: what has changed in Portugal
Capital gains and tax implications for the seller
When it makes sense to sell to a fund and when it does not
Frequently asked questions
What are real estate investment funds and how do they operate in Portugal
A real estate investment fund is a financial vehicle that pools capital from multiple investors with the objective of acquiring, managing and generating returns from property assets. In Portugal, these funds are regulated by the Securities Market Commission and may be open or closed, domestic or international, with different investment strategies.
In the residential market, the funds that most actively buy housing typically fall into three categories. Residential rental funds, which acquire properties to place on the long-term rental market, often with controlled rents or in partnership with the State. Return-oriented investment funds, which buy to rent at market prices, maximising the portfolio's profitability. And development or rehabilitation funds, which acquire properties to renovate and resell, often focusing on urban regeneration.
The growing presence of these funds in the Portuguese market is partly a consequence of the low interest rate policy of previous years, which directed institutional capital towards property as a yield alternative. But it also reflects a structural interest from international investors in the stability and potential of the Portuguese housing market, particularly in cities with high and consistent rental demand.
The advantages of selling to an investment fund
For a seller who wants to sell, a transaction with an investment fund has distinct characteristics from a sale to a private buyer. These characteristics can be advantageous in certain circumstances.
Speed and certainty of completion
One of the most significant advantages of selling to a fund is the speed and certainty of transaction completion. Investment funds do not depend on bank mortgage approval, which eliminates one of the greatest sources of uncertainty and delay in conventional property transactions. When a fund makes an offer, it typically has the capital available and the decision-making structure needed to move quickly.
For a seller who needs liquidity within a defined timeframe, who wants to close the deal without the risk of a mortgage approval failing at the last moment, or who simply values predictability in the process, this certainty of completion has a real value that should not be underestimated.
Direct transaction with no need to prepare the property
Investment funds, particularly those focused on rehabilitation or rental with prior renovation, typically buy properties as they stand, without requiring the seller to carry out preparation works, home staging or any intervention before the sale. For sellers who are selling older properties, properties that need work or inherited properties that have not been occupied recently, this characteristic can save time, money and the stress associated with preparing a property for the market.
Lower process exposure
When selling to a private buyer, the process includes preparing the property, listing it on portals, viewings with multiple potential buyers and exposing the private space to strangers for weeks or months. A transaction with a fund is typically far more discreet: there are technical assessments, direct negotiation with the buying entity and a process involving a much smaller number of people.
For sellers who value privacy, who have tenants they do not want to disturb or who simply prefer a less exposed process, selling to a fund can be a more comfortable alternative than the open market sale process.
Possibility of portfolio sale or properties with complexity
Investment funds are frequently the only buyers capable of acquiring multiple properties simultaneously. For sellers with more than one property to sell, such as in the case of an inheritance with several properties or an investment portfolio, the possibility of closing everything in a single transaction with a single buyer is an enormous simplification of the process.
Similarly, funds have the capacity to deal with properties that have documentary complexities, occupation issues, licensing questions or other characteristics that deter private buyers. This ability to absorb complexity is a relevant advantage for certain types of property.
Points to consider carefully
The advantages above are real, but a transaction with an investment fund also has characteristics the seller should analyse carefully before deciding.
The price tends to be below market value
This is the most important point to consider. Investment funds buy properties as portfolio assets and the logic guiding their offer is the expected return on investment, not the emotional value or the maximum price the market could pay. In practice, fund offers tend to be below what a private buyer, with more time and personal motivation, would be willing to pay for the same property.
The discount varies significantly depending on the type of fund, the investment strategy and the specific characteristics of the property, but it can range from 10% to 25% below market value. For the seller, the central question is whether the process advantages compensate for this price differential. Sometimes they do; other times, a well-executed conventional sale would produce a significantly better financial result.
Before accepting any proposal from a fund, it is essential to have a rigorous property valuation carried out by professionals with knowledge of the local market. Only with this reference is it possible to understand whether the discount implicit in the fund's proposal is reasonable or excessive relative to what the open market would offer.
The contract terms deserve careful legal analysis
Investment funds are professional entities with experienced legal teams. The contracts they propose are typically more complex than those of a conventional transaction and may include clauses that favour the fund in contingency situations, specific timescales the seller needs to understand, suspensive conditions relating to technical or legal due diligence and price adjustment mechanisms depending on elements discovered during the analysis.
Signing a contract with a fund without independent legal support is a mistake that can have significant financial consequences. A property law specialist with experience in institutional transactions is indispensable to protect the seller's interests in this process. The documents required for the sale of a property are a starting point, but in a transaction with a fund the due diligence goes well beyond the usual documentation.
The tenant situation has specific implications
If the property is tenanted, the sale to a fund does not eliminate the obligations towards the tenant. The tenant's right of first refusal, established under Portuguese law, applies regardless of whether the buyer is a private individual or a fund. The seller is obliged to notify the tenant of the conditions of the sale and give them the opportunity to exercise the right of first refusal on the same terms.
Additionally, the existing tenancy agreement transfers with the sale, meaning the fund acquires the property with all the obligations of the current rental contract. For funds whose plan is to carry out works or change the use of the property, the existence of a tenant on an active contract can be a factor that affects the proposed price or the transaction conditions.
The identity and reputation of the fund matter
Not all real estate investment funds are equal. There are funds with solid reputations, transparent processes and a track record of well-executed transactions in Portugal. There are also less transparent investment vehicles, some based in jurisdictions with lighter regulation, whose due diligence processes may be longer, more intrusive or less certain.
Before advancing any negotiation, the seller should investigate the identity of the fund, its regulation, its track record in the Portuguese market and, wherever possible, speak with other sellers who have transacted with the same entity. A fund that does not provide this information transparently is a warning sign that should be taken seriously.
How to position the sale: open market versus direct transaction
For a seller who has received a fund proposal, or who is considering selling and has funds as potential buyers, the central question is: should I proceed directly with the fund or put the property on the market and explore all options?
The answer depends on several factors. If the priority is speed and certainty of completion, and if the discount implicit in the fund's proposal is acceptable given the property's context, the direct transaction may be the best option. If the priority is maximising the value obtained and the property has characteristics that make it attractive to private buyers, the open market will likely produce a better result.
There is also a third route that many sellers do not explore: using the fund's proposal as a benchmark and a pressure point in a negotiation with the open market. A concrete offer from an institutional buyer, even if below market value, is a real signal of interest that can accelerate the decision of private buyers who may be considering the same property.
In this context, Engel & Völkers has been accompanying Portuguese sellers in exactly these situations, helping to assess fund proposals, compare them with the open market potential and define the strategy that best serves the seller's interests in each specific situation.
The regulatory context: what has changed in Portugal
The increasing presence of investment funds in the Portuguese housing market has not gone unnoticed by policymakers. In recent years, the Portuguese government has implemented measures aimed at regulating the activity of large institutional investors in the housing market, particularly in areas of higher pressure such as Lisbon and Porto.
Among the measures adopted are restrictions on short-term rental in certain areas, tax incentives for affordable rental, and discussions around limitations on the acquisition of housing for purely speculative purposes. This regulatory context is evolving and may influence both the behaviour of funds and the terms of transactions.
For a seller selling to a fund, the regulatory context may be relevant if the fund's intended use of the property is subject to specific restrictions. If the fund plans to convert a residential property to short-term rental in a restricted area, or plans to reclassify the use of the property, these intentions may have implications for the execution of the project and, indirectly, for the transaction conditions.
It is always advisable for the seller to understand, as far as possible, what the fund's plan is for the property it is acquiring. Not because the seller is responsible for what the buyer does with the property after the sale, but because this understanding may reveal risks or constraints that affect the certainty of completion or the contract terms.
Capital gains and tax implications for the seller
Regardless of who the buyer is, selling a property in Portugal potentially generates a capital gain subject to personal income tax. The calculation of property capital gains is based on the difference between the updated acquisition value and the sale value, with possible deductions for improvement costs and intermediation fees.
For properties that were the seller's permanent primary residence and where the proceeds are reinvested in another permanent primary residence within a defined period, there are mechanisms for partial or total exclusion of the capital gain. This regime applies regardless of whether the buyer is a private individual or a fund.
Selling to a fund at a price below market value can paradoxically reduce the assessed capital gain and, consequently, the tax burden on the seller. But this tax benefit should never be the main argument for accepting a lower price: the final net impact, after considering the price differential and the tax differential, must always be assessed on a case-by-case basis with an accountant or tax adviser.
When it makes sense to sell to a fund and when it does not
Selling to an investment fund makes particular sense in certain circumstances: when the property is in poor condition and the seller does not want to invest in works before selling; when there is urgency for liquidity and certainty of completion is the priority; when there are documentary or occupation complexities that deter private buyers; or when the property portfolio is large and simplifying the process is a concrete objective.
It does not make sense to sell to a fund when the property is well positioned in the market and has characteristics that attract motivated private buyers; when the price proposed by the fund is significantly below market value and the seller has time to explore alternatives; or when the proposed contract terms are unfavourable and the fund has no flexibility to adjust them.
The Engel & Völkers Market Study confirms that the Portuguese property market maintains robust demand from private buyers, particularly in quality urban segments. In many cases, the best strategy for a seller remains the open market, with careful presentation, well-positioned pricing and the support of a team experienced in negotiation.
If you are thinking of selling your property and want to understand whether a fund transaction or the open market is the best option for your situation, speak with the experienced property team at Engel & Völkers. With the right market knowledge and understanding of the different types of buyers, you can make this decision with the information it deserves and the confidence of knowing what you are doing.
PROPERTIES IN PORTUGAL
Engel & Völkers Portugal
- New
- New
- New
Frequently asked questions
How can I tell whether a fund's offer is within fair value or too far below the market?
The only way to assess a fund's proposal rigorously is to have an independent market reference. This means obtaining a professional property valuation carried out by a consultant with access to real transaction data in the same area, not just the asking prices currently listed. With this reference in hand, it is possible to calculate the discount implicit in the fund's proposal and assess whether that discount is justified by the property's specific characteristics, by the speed of process or by other concrete advantages. A discount of 5% to 10% may be acceptable in a situation where quick completion is the priority; a discount of 20% or more is difficult to justify for a property in good condition and well located.
Do investment funds always pay in cash, or can they offer deferred payment terms?
The majority of real estate investment funds pay in cash, which is one of their main advantages over buyers using bank financing. However, there are funds that, depending on their structure and the scale of the transaction, may propose phased payments, particularly when the transaction involves multiple properties or when there are suspensive conditions that need to be met before full payment. It is essential that the payment terms are clearly defined in the contract and that the seller understands precisely when and under what conditions payment will be made. A specialist lawyer is indispensable to ensure there are no ambiguities in this regard.
Can a fund make a proposal conditional on the outcome of due diligence, and what does that mean for the seller?
Yes, it is very common for funds to make proposals conditional on the outcome of a technical and legal due diligence of the property. This means the proposal presented is binding only if the due diligence does not reveal problems that significantly alter the fund's assessment. For the seller, this implies two risks: the risk of the price being revised downward if due diligence reveals issues, and the risk of the deal not proceeding if the problems found are sufficiently significant. To mitigate these risks, the seller should, before signing any exclusivity agreement with a fund, have their own due diligence carried out, or at least have a thorough knowledge of the documentary and physical state of the property, so as not to be caught off guard by the buyer's due diligence.
What happens to a tenant when a property is sold to an investment fund?
The tenant has the same rights regardless of whether the buyer is a private individual or an investment fund. The right of first refusal, which must be exercised within a defined period after notification of the sale terms, applies in full. The existing tenancy agreement transfers to the new owner on the same terms, and the tenant's rights are not affected by the change of ownership. In some cases, funds that want to free the property for works or change of use will attempt to negotiate a voluntary departure with the tenant in exchange for financial compensation. This negotiation is between the fund and the tenant, but the seller should be aware that the existence of a tenancy agreement with significant remaining duration can affect the price or terms proposed by the fund.
Is there any difference between selling to a domestic fund and selling to a foreign fund in Portugal?
From a legal perspective, foreign funds operating in Portugal are subject to the same property acquisition rules as domestic funds, and the seller's rights are the same in either case. The main practical difference tends to lie in the due diligence process and decision timescales. Foreign funds, particularly larger ones, tend to have more formalised due diligence processes with more layers of internal approval, which can make the process more time-consuming despite their cash payment capacity. The language and contractual structure may also differ, making it even more important to have an experienced lawyer who ensures the terms are clear and that the seller's interests are protected in any eventuality.
Can a seller negotiate the terms of a fund's proposal, or are they always take-it-or-leave-it?
Investment fund proposals are negotiable, like any other property offer. The degree of flexibility varies depending on the fund, the strategic importance of the property to its portfolio and the competition for the acquisition. Elements that are frequently negotiable include the price, the completion timescales, the due diligence conditions, the warranties on the state of the property and the treatment of contingencies. A seller who enters a negotiation with a fund without good advice has far less negotiating capacity than one who has alongside them an experienced property consultant and a specialist lawyer who know the standard terms in these types of transactions.
What types of properties are most of interest to funds active in the Portuguese residential market?
The most active funds in the Portuguese residential market typically have clear preferences. Residential rental funds look for one to three-bedroom apartments in areas with high rental demand, such as Lisbon, Porto and the main municipalities of their metropolitan areas. Rehabilitation funds look for entire buildings or groups of properties in historic areas or those undergoing regeneration, where there is significant appreciation potential following intervention. Short-term rental funds look for properties with conversion potential in established tourist areas, although regulatory restrictions in this segment have constrained this demand in certain areas. For smaller properties, in peripheral areas or with very specific characteristics, fund interest tends to be lower and the proposals reflect the additional complexity of absorbing these assets.
What should I do if I receive an unsolicited proposal from an investment fund for my property?
Neither reject it immediately nor accept it hastily. The first step is to obtain an independent valuation of your property to understand whether the proposal reflects market value or not. The second is to consult a property law specialist before signing any document, even if it is only a letter of intent or exclusivity agreement. The third is to understand who the fund is, its market reputation and its track record in Portugal. And the fourth is, if you have doubts about whether the open market would produce a better result, to consult an experienced property consultant who can give an objective perspective on the alternatives available. Receiving an unsolicited proposal creates no obligation to accept it. It creates the opportunity to assess calmly whether this is or is not the best option for your specific situation.
You may also be interested in
 15 questions to ask your real estate agent before buying an apartment
 How to buy a house with sea view in Portugal
 Guide to Buying a Home in Setúbal and Making the Most of the Region
 Tips for buying a rural house in Portugal with confidence
 How to Negotiate a Mortgage
 Complete guide to buying and selling property in Portugal
 Price per square meter of an apartment in Portugal: Everything you need to know
 Mortgage amortization: understand how to reduce years and interest on your home loan
 Private Office Market Report 2026
- 2 min.
- 03.12.2025
 Informe de mercado Engel & Völkers Portugal
FOR MORE INFORMATION
Contact us
Engel & Völkers Portugal
Av. da Liberdade 196, 7 andar
1250-096 Lisboa, Portugal
Tel: +351 210 200 490